ISA Contribution Split Planner (UK)
Compare different ways to split your ISA contributions between cash and investments over time.
- Free
- No sign-up
- Uses the 2026-27 rules
Results are estimates only and not financial advice.
ISA Contribution Split Planner
The Advanced ISA Planner turns a percentage split like this into pound values, year by year, for two scenarios (one-off £14.99, no subscription).
Advanced ISA Planner
Compare ISA scenarios side by side
£14.99 one-off, no subscription
This free planner compares two percentage splits; the Advanced ISA Planner can compare scenarios side by side across several tax years.
When a single calculator is not enough, the Advanced ISA Planner lets you set up longer-term scenarios, combine different ISA types, including cash ISAs, and model multiple tax years in one place.
- Combine Cash and Stocks & Shares ISAs
- Model multiple tax years and allowances
- Adjust returns, contributions, and time horizons
- Compare scenarios side by side
A paid tool: a one-off purchase of £14.99, with no subscription. The free calculators are separate from the planner. See the refund policy. Figures are illustrations, not forecasts.
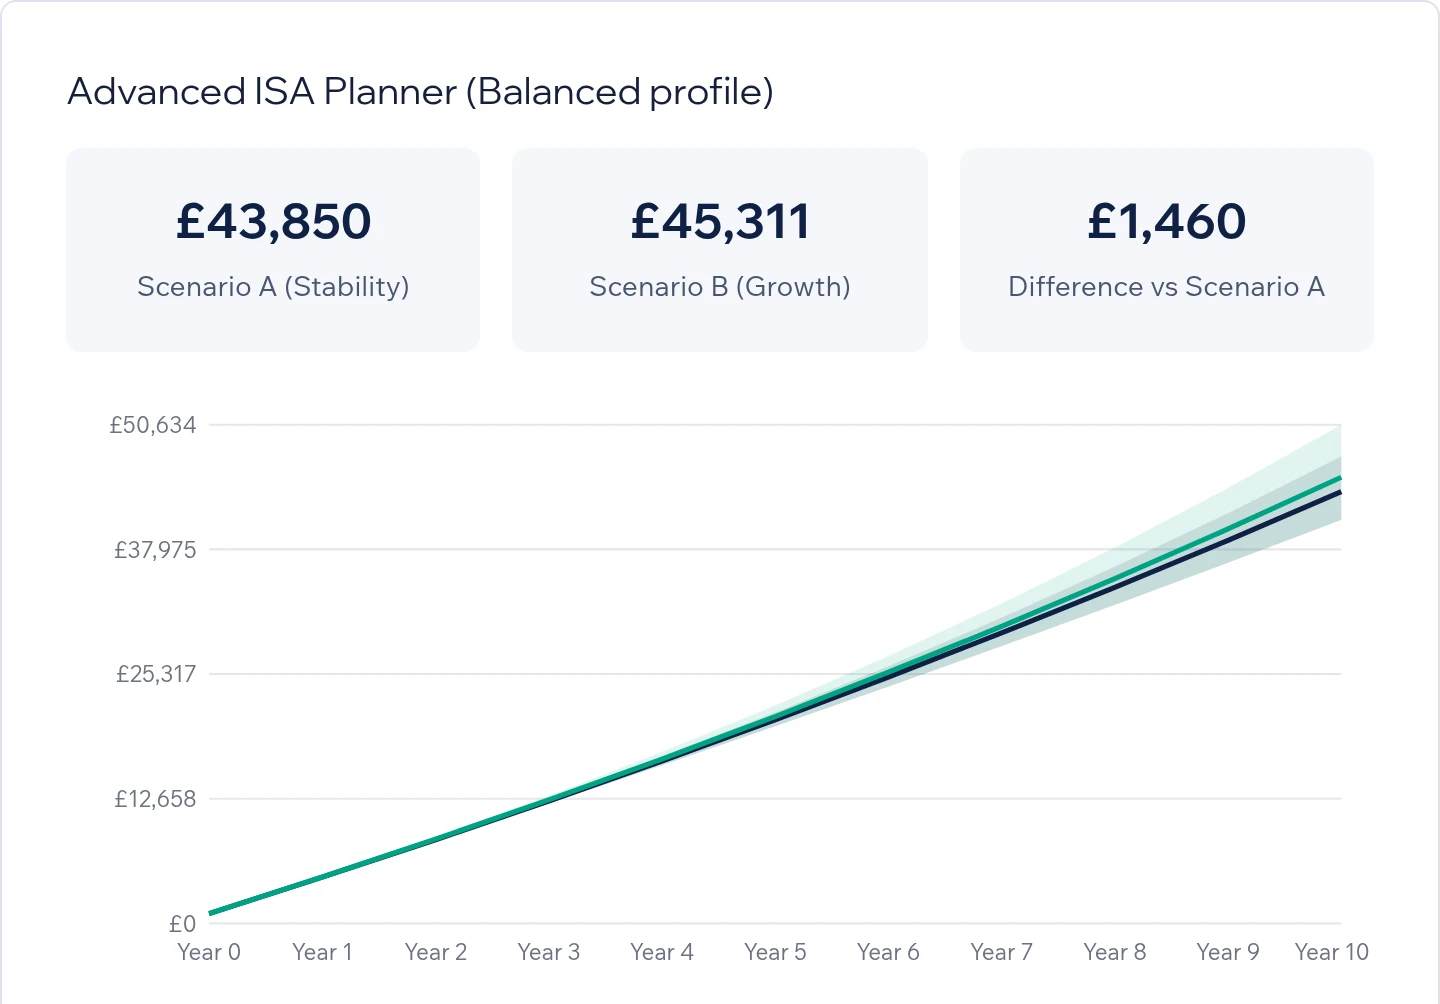
ISA contribution split scenarios
- Scenario A: Lower volatility; returns are not guaranteed
- Scenario B: Higher potential for growth over time, and for loss
- Outcomes: Compare growth over time
Want to explore a different approach? Adjust your allowance strategy with the ISA Allowance Checker
How to use the ISA Contribution Split Planner
- Enter your contributions (and any lump sum)
- Choose your time horizon and risk profile
- Compare contribution split scenarios
Splitting your ISA allowance between cash and investments
Your £20,000 ISA allowance for 2026-27 can be divided between Cash ISAs, which pay interest, and Stocks and Shares ISAs, which invest in funds, shares and bonds and can rise or fall in value. This planner compares two illustrative percentage splits based on your time horizon and risk preference. It does not estimate a value in pounds.
- From 6 April 2027, savers under 65 will be able to put no more than £12,000 a year into cash ISAs (GOV.UK). The planner checks each tax year against that limit and shows when part of a scenario's cash share would need to go into a Stocks and Shares ISA instead. See the cash ISA limit from April 2027 explained.
- You can pay into more than one Cash ISA or Stocks and Shares ISA in the same tax year, as long as the total stays within the allowance (GOV.UK: how ISAs work).
- Our reference page lists all ISA rules for this tax year and the next, each with its gov.uk source.
ISA rules on this page are correct as of 26 September 2026. For every rule with its gov.uk source, see ISA rules at a glance.
To estimate each part in pounds, use the Cash ISA Calculator and the Stocks and Shares ISA Calculator.
Where to go next
Review & refine
Change the risk profile or the contribution split and run it again to see how the percentages change. The planner does not recommend a split.
Check allowance usage
The ISA Allowance Checker shows how much of this tax year's allowance is left, from the amount already paid in.
Illustrate growth
The Stocks and Shares ISA Calculator shows how contributions could grow at a return you enter. It is an illustration, not a forecast.
ISA Contribution Split Planner FAQs
This tool compares different ways to split ISA contributions between Cash ISAs and Stocks & Shares ISAs, based on your time horizon and risk preference.
No. The planner shows illustrative scenarios to support decision-making. The most suitable option depends on your personal circumstances and tolerance for risk.
No. Any outcomes shown are estimates only. Investments can go down as well as up, and past performance is not a guide to future returns.
No. The planner focuses on contribution allocation and high-level growth assumptions. Fees, inflation, and tax treatment vary by provider.
Yes. Many investors adjust their ISA allocation over time as goals, risk tolerance, or market conditions change.